The Baku climate summit ended on 24 November 2024 with a new climate finance goal: at least $300 billion a year by 2035. What it includes and what it means for business.
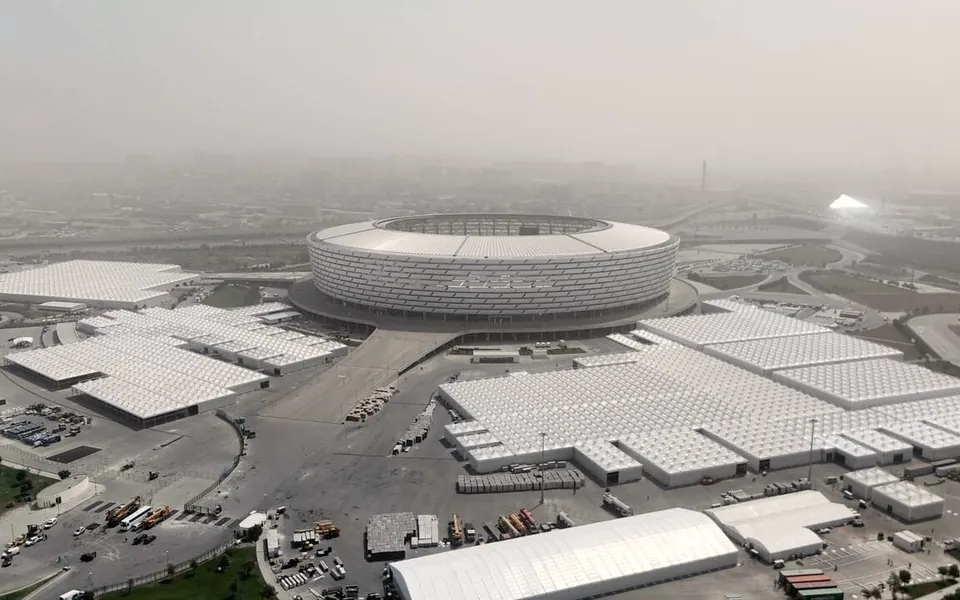
The United Nations climate summit (COP29), held in Baku (Azerbaijan) from 11 to 23 November 2024, ended in the early hours of Sunday 24 November with a new collective goal for international climate finance. The negotiations ran past the scheduled closing date. The results are gathered under the name of the Baku Climate Unity Pact and include decisions on finance and on carbon markets.
The finance
The new goal has two figures. The first is what developing countries asked for: $1.3 trillion a year by 2035, to be provided by all actors, public and private, and directed exclusively to those countries. The second is the commitment by developed countries, which will continue to lead and will mobilise at least $300 billion a year by 2035, triple the existing goal of $100 billion, which according to Climate Home News was reached in 2022, two years late.
Those $300 billion may come from a wide variety of sources, public and private, bilateral and multilateral. The text encourages developing countries to contribute on a voluntary basis, and South-South cooperation and multilateral development banks join in under that framework. Developed countries had proposed including China and the Gulf states as official donors, which developing countries rejected.
The agreement also includes guidelines for multilateral banks and climate funds to ease access to finance, measures to mobilise private capital through instruments such as guarantees and local-currency financing, and a Baku to Belém roadmap towards the $1.3 trillion, to be led by the presidencies of Azerbaijan and Brazil. The decision will be reviewed in 2030.
Carbon markets and what was not agreed
Baku also closed the last outstanding element of the Paris Agreement: the Article 6 rules for carbon markets. The UN-supervised mechanism (Article 6.4) now has guidelines for measuring emission reductions and addressing reversal risks for removals, and bilateral trading of reductions between countries (Article 6.2) has transparency and traceability rules to avoid double counting of credits.
There was no progress, by contrast, on mitigation; the implementation of the Dubai agreements on the energy transition was not secured, nor was an agreement reached on the just transition agenda, according to the note from Spain’s Climate Change Office. Several developing countries, including India, Nigeria, Cuba and Bolivia, criticised the size of the finance goal; India’s delegate, Chandni Raina, called it too small and too distant. European Commissioner Wopke Hoekstra described it as the start of a new era for climate finance, and UN Secretary-General António Guterres said he had hoped for a more ambitious outcome on finance and mitigation, but that the agreement is a base on which to build.
What it means for business
For companies, the agreement creates no direct obligations: it sets a goal for governments and financial institutions. But it indicates where international public finance is heading, seeking to mobilise private capital, and it completes the rules for carbon markets, which affect anyone buying or generating carbon credits. Companies with energy, water or infrastructure projects in developing countries can follow how guarantees, local-currency financing and climate funds take shape.
It is worth reviewing which of the company’s projects could qualify for multilateral financing, which carbon-credit rules apply to it and how European sustainability reporting rules are evolving. Ask your adviser how this applies to you.
Figures are approved in a night; delivering them takes years.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.