On 24 July 2025 the ECB held rates for the first time since 2024: the deposit facility rate stayed at 2%. Why it paused and what it means for mortgages and deposits.
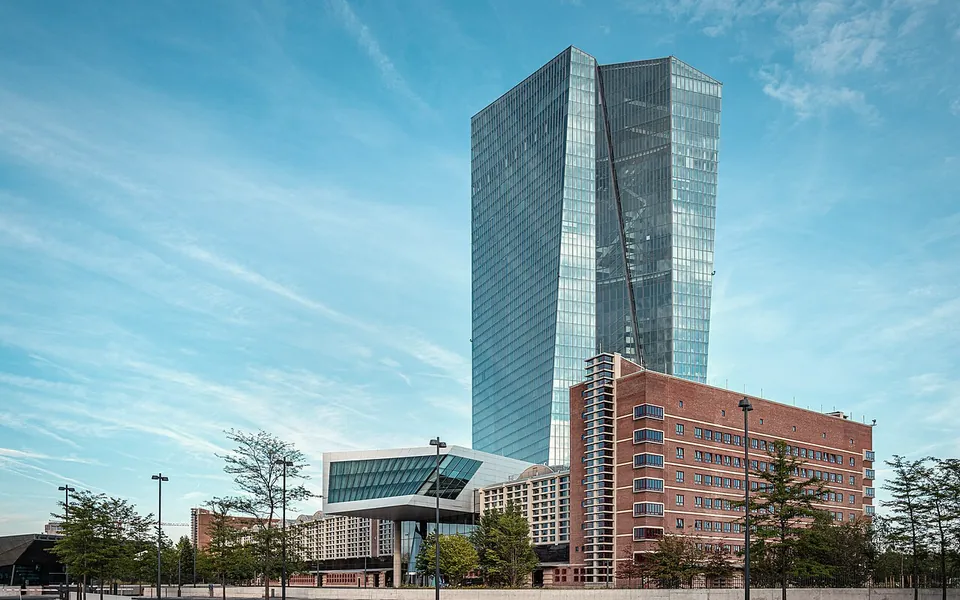
The Governing Council of the European Central Bank (ECB) decided on 24 July 2025 to leave its three key interest rates unchanged. The deposit facility rate, the benchmark for its policy, stayed at 2.00%, after eight consecutive quarter-point cuts since June 2024, when it stood at 4%.
Why it paused
Euro-area inflation had returned to around 2%, the ECB’s target, and the economy was holding up better than expected despite the trade war. With rates already at a level the ECB itself regards as close to neutral, neither holding back nor stimulating the economy, the Council preferred to wait and see the effect of tariffs before deciding whether further cuts were needed.
Christine Lagarde, its president, described this as a good position from which to wait and repeated that decisions are taken meeting by meeting, depending on the data. Trade talks between the European Union and the United States were in their final stretch: the deal was announced a few days later, on 27 July, with a general 15% tariff on most European exports.
The market reaction
The decision was fully expected and barely moved markets. Twelve-month Euribor, the benchmark for most variable-rate mortgages in Spain, held at around 2.1%, far below the 4% of late 2023. Markets began to assume that the cutting cycle had ended or was about to.
What it means for mortgages and savings
For those with a variable-rate mortgage, most of the relief had already come through: 2025 resets were made at a much lower Euribor than a year earlier. For those taking out a new mortgage, the gap between fixed and variable rates had narrowed, and it is worth comparing both options over the full term of the loan.
For savers, the pause halts the fall in returns on deposits and Treasury bills, which had dropped markedly since 2024. For companies, floating-rate borrowing stops getting cheaper in the short term. Ask your adviser how this applies to you.
Knowing when to stop is part of a central bank’s craft.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.