On 14 February 2017 Toshiba postponed its results, flagged a ¥712.5 billion loss at Westinghouse and saw its chairman resign. What it teaches anyone buying a business.
On 14 February 2017 Toshiba, the Japanese industrial conglomerate, asked for and obtained an extra month, until 14 March, to file its third-quarter report (October to December 2016). The same day it said, according to Reuters, that its US nuclear subsidiary Westinghouse would force it to book a loss of ¥712.5 billion, about $6.3 billion, and that its shareholders’ equity would turn negative. The figures have not yet been audited and the company warned they could change.
What has happened at Westinghouse
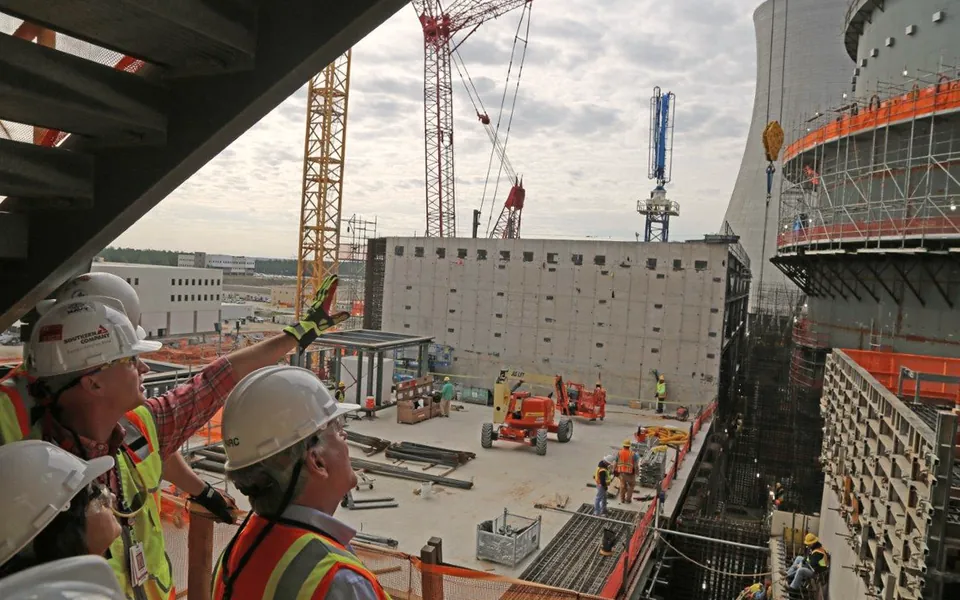
In December 2015 Westinghouse Electric Company, Toshiba’s nuclear subsidiary, bought the nuclear construction division of Chicago Bridge & Iron (CB&I), Stone & Webster. It then estimated goodwill, the part of the price above the value of the assets acquired, at about $87 million. On 27 December 2016 Toshiba warned that the cost of completing the AP1000 reactor projects in the United States would far exceed forecasts and that goodwill could reach several billion dollars.
A second problem, over internal control, was added to that accounting one. According to Toshiba, on 8 and 19 January it received internal reports suggesting that controls over the purchase price allocation for Stone & Webster were inadequate, and on 28 January a Westinghouse manager said that the subsidiary’s senior management was applying inappropriate pressure to speed up that process. The audit committee commissioned an investigation from the law firm Nishimura & Asahi and Westinghouse hired K&L Gates. The lawyers and the auditor need about another month, and Toshiba says that for now it has found no items that would require its quarterly accounts to be corrected.
The consequences
Chairman Shigenori Shiga resigned the same day to take responsibility for the loss on the Stone & Webster purchase; he will stay on as an executive officer until the shareholders’ meeting in June to concentrate on resolving Westinghouse’s problems. Reuters noted that Shiga had been head of Westinghouse and that it was the first top-level departure since the nuclear problems surfaced in December.
The company, which had an accounting scandal in 2015, has also seen its value fall: shares dropped 8% on 14 February, to a market capitalisation of about ¥973 billion, less than half the mid-December level, according to Reuters.
To strengthen its balance sheet, Toshiba decided on 27 January to split off its memory business into a subsidiary and is seeking third-party capital. On 14 February chief executive Satoshi Tsunakawa said it is weighing several offers and, according to Reuters, that it is prepared to give up a majority of that business, when it had previously planned to sell just under 20%. Toshiba also announced that it will withdraw from building nuclear plants overseas.
What it teaches anyone buying a business
The case is not only about nuclear power: it is about an acquisition whose value was revised long after it closed. First, fixed-price construction contracts, such as those for reactors, can cost more than forecast, and that cost changes the value of what was bought. Second, allocating the purchase price to the assets and liabilities acquired is an accounting process with its own risk: it should be documented and reviewed by someone outside the team that closes the deal.
Third, internal warnings work if they reach someone who must act: here the January reports led the audit committee to investigate before the accounts were published. In an acquisition it is also worth reviewing what guarantees the seller gives, whether there are price-adjustment clauses or part of the payment held back until the value of what was acquired is confirmed, and who reviews internal controls afterwards.
A purchase does not end at signing: the value of what was bought is tested afterwards, and internal controls are what make the number credible.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.