In one week the German payments group Wirecard went from delaying its accounts to filing for insolvency on 25 June 2020, after €1,900 million could not be found. What happened and what it teaches.
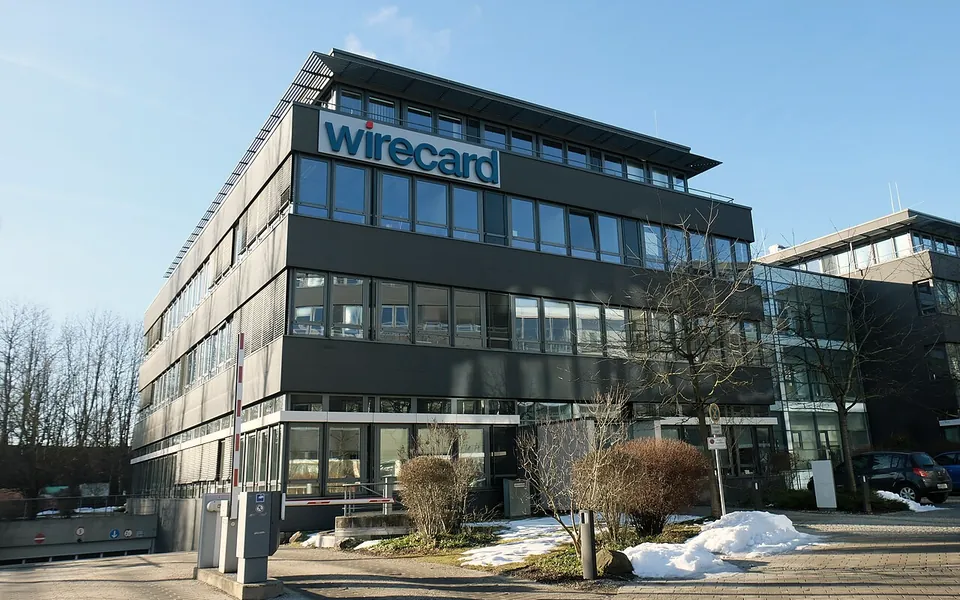
Wirecard, based in Munich, processed electronic payments for merchants around the world, had almost 6,000 employees in 26 countries and had joined the DAX, the index of Germany’s thirty largest listed companies, in 2018 at a valuation of €24,000 million. On 18 June 2020 it was due to present its 2019 accounts. Instead it announced that its auditor, EY, had not been able to obtain sufficient evidence that €1,900 million held in trust accounts at two Asian banks existed. It was the fourth time it had postponed those accounts.
The doubts were not new. Since 2019 a series of Financial Times articles had pointed to accounting irregularities in the group’s Asian operations. In April 2020 a special audit by KPMG had been unable to verify a large part of the profits reported between 2016 and 2018. And in early June the Munich prosecutor’s office was investigating all four members of the management board for market manipulation, over the way that report was communicated, after Germany’s financial regulator, BaFin, referred the case to prosecutors.
A week of collapse
According to Wirecard itself, there were indications that false balance confirmations had been provided to the auditor in order to deceive it. The two Philippine banks named, BDO and BPI, denied that Wirecard was their client and said the documents were forged. On 19 June the chief executive, Markus Braun, resigned. On 21 June the Philippine central bank said the money had never entered the country, and on 22 June Wirecard said there was a prevailing likelihood that those balances did not exist, and dismissed its chief operating officer, Jan Marsalek.
That Monday evening Braun turned himself in to Munich prosecutors and was arrested on suspicion of inflating the balance sheet and sales volume with fictitious income from transactions with third-party acquirers, possibly together with others. He was released on bail of €5 million and remains a suspect. On 25 June the new management applied for insolvency at a Munich court because of impending insolvency and over-indebtedness, and was considering doing the same for its subsidiaries. The shares fell by almost 80%, to a valuation of less than €400 million, and creditors stand to lose billions. Prosecutors widened the investigation to other people.
Lessons in corporate governance and supervision
The first lesson is that cash is the easiest asset to check, which is why the auditor confirms it directly with the bank. Here, according to Wirecard itself, the confirmations appeared to be false, and the funds depended on an outside trustee. The second is that when a board and its audit committee receive warnings over months, from the press, from a special report or from an investigation, they must test them independently of management and with the same insistence with which they press for the accounts to be closed.
The third concerns supervision. The head of BaFin, Felix Hufeld, called the case a complete disaster on 22 June, and the auditor and the supervisor have begun to face questions about what they saw and when. A deeper question remains open: who supervises what in a group that combines a bank, technology and subsidiaries across half the world, and how far each one’s checks reach.
What to review
For those who hold investments, the case is a reminder that a well-known company with a heavy weight in an index can have problems the market is slow to see. It is worth knowing how much exposure there is to a single issuer, and bearing in mind that when an auditor does not sign the accounts, the financial information is unreliable until the matter is clarified. For merchants who are paid through a payment processor, it is worth knowing where the funds for pending payments are held and what alternative exists if the provider fails. Ask your adviser how this applies to your case.
When the money cannot be verified, neither size nor prestige is enough.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.