On 9 October 2017 the Swedish Academy awarded the Economics Nobel to Richard Thaler for bringing psychology into economics. What it said about saving for retirement and what a company can learn from it.
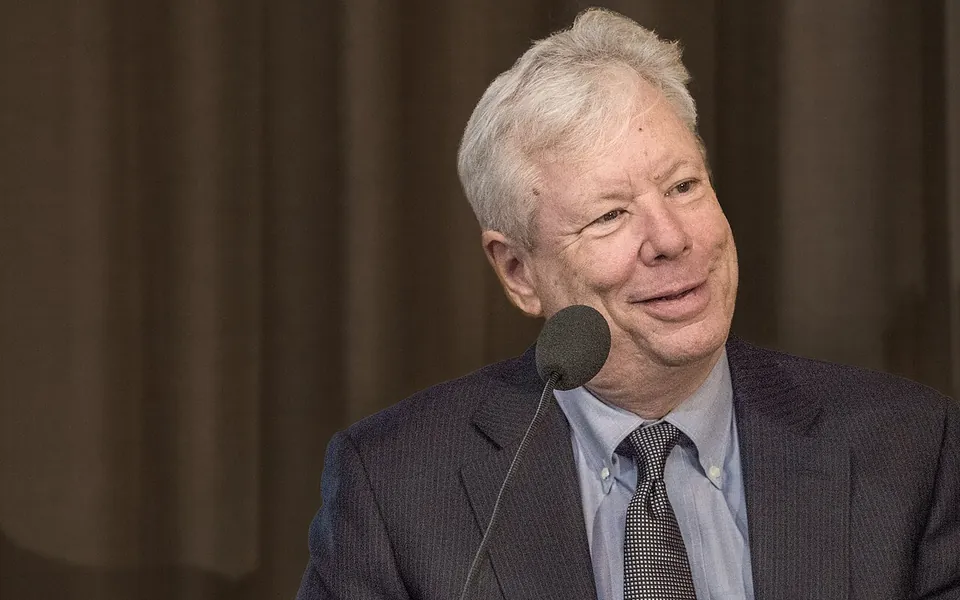
On 9 October 2017 the Royal Swedish Academy of Sciences awarded the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel, known as the Economics Nobel, to Richard H. Thaler of the University of Chicago Booth School of Business, “for his contributions to behavioural economics”. Thaler was born in 1945 in East Orange, New Jersey. The prize, 9 million Swedish kronor, goes to him alone.
What the Academy rewarded
According to the Academy, Thaler has built psychologically realistic assumptions into the analysis of economic decisions. Classical theory assumes that people handle all the information, always carry out their plans and care only about personal gain. Thaler studied three traits that depart from that model and that systematically affect decisions and markets: limited rationality, social preferences and lack of self-control.
On limited rationality, he developed the theory of “mental accounting”: we simplify financial decisions by creating separate accounts in our heads, each with its own rules, and judge each decision by its effect on that account rather than on our wealth as a whole. The Academy gives the example of the household that sets money aside for bills and for holidays. Sometimes that costs money, as when someone takes out an expensive loan instead of using long-term savings; at other times it protects those savings. Thaler also used loss aversion to explain the “endowment effect”: we ask more for something we own than we would pay to get it. He was also one of the founders of behavioural finance.
On social preferences, he showed that ideas of fairness weigh on decisions. Consumers accept a price rise less readily when it comes from high demand than when it comes from higher costs, and it is hard to win acceptance for a nominal pay cut, although people tolerate a rise below inflation, which is a loss in real terms.
Self-control and saving for retirement
The third piece is self-control. With Hersh Shefrin, Thaler proposed the “planner–doer” model: one self that thinks about long-term happiness and another that is driven by immediate goals. Giving in to short-term temptation is, according to the Academy, an important reason why plans to save for old age fail. Hence his applied work on “nudges”, a term he coined: helping people decide better without banning anything, often through the default option, the one that applies if you do not choose another.
On saving, the Academy cites a 2001 study in which automatic enrolment in a US workplace savings plan raised participation from 49% to 86%. Thaler and Shlomo Benartzi designed the “Save More Tomorrow” programme: workers commit part of their future pay rises to saving; it is voluntary and they can leave whenever they wish. According to an estimate by the two that the Academy reports, about 4.1 million Americans were in some kind of automatic escalation plan by 2011, and by 2013 that mechanism had raised annual saving by $7.6 billion. The United Kingdom has launched a national plan with automatic enrolment in which only about 12% of workers have opted out.
What a company or a family can learn
For companies, the lessons reach pricing, pay and employee savings plans. A price rise driven by demand can be seen by customers as abusive; a pay review is judged from the reference point of current pay; and the design of a workplace savings plan, starting with the default option, changes how many employees use it.
For a family, mental accounting is a reminder to look at wealth as a whole: it is worth knowing whether long-term savings are being kept while an expensive loan is paid elsewhere, and whether the rules one has set protect or cost money. Automatic enrolment and saving more as pay rises are the two ideas the prize-winning research has studied. Ask your adviser how to apply it to your case.
Understanding how we really decide is the first step towards deciding better.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.