On 2 March 2017 Snap, the parent of Snapchat, made its debut on the New York Stock Exchange at $17 a share and closed its first day up 44%. The shares the public buys carry no vote.
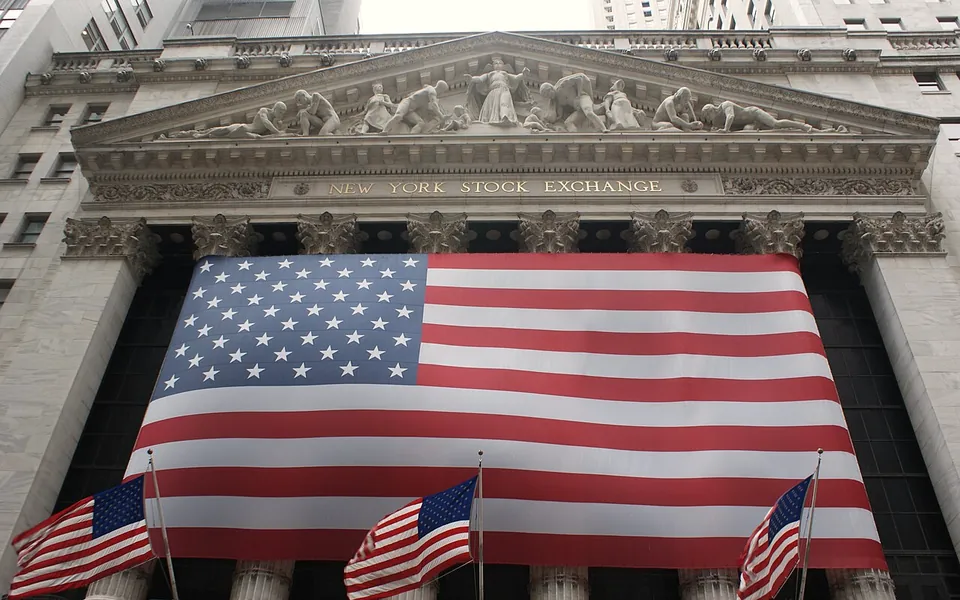
Snap Inc., the US company that owns the Snapchat messaging app, began trading on Thursday 2 March 2017 on the New York Stock Exchange (NYSE) under the symbol SNAP. On 1 March it had set the offer price at $17 a share, above the $14 to $16 range in the prospectus filed with the US Securities and Exchange Commission (SEC) on 24 February. It placed 200 million shares, 145 million new ones and 55 million sold by existing shareholders, for a total of $3.4 billion.
The market debut
According to the business press, the 2 March session closed at $24.48, 44% above the offer price, leaving the company valued at around $28 billion.
The prospectus shows a company that is growing fast and losing money: in 2016 it had revenue of $404.5 million, almost seven times the $58.7 million of 2015, and a net loss of $514.6 million, against $372.9 million the year before. Snapchat had 158 million daily active users on average in the fourth quarter of 2016.
The corporate governance debate
Snap has three classes of shares. Class A, the one the public buys, carries no vote except where Delaware law, the state where it is incorporated, requires one. Class B has one vote per share and Class C ten. Class C belongs to the two co-founders, Evan Spiegel, the chief executive, and Robert Murphy, the chief technology officer, and according to the prospectus will represent about 88.5% of the voting rights after the offering.
The prospectus itself acknowledges the consequences: Class A holders cannot vote, nominate directors or put proposals to the shareholders’ meeting, and Snap is not required to hold advisory votes on executive pay. The founders’ control could delay or prevent a change of control. Snap says it will not use the NYSE exemption for “controlled companies”, which allows some board-independence rules to be disregarded.
Multi-class share structures have existed for some time at large technology companies; what the press highlighted in Snap’s case is that the public was given no vote at all. Some analysts quoted in the British press criticised the terms of the flotation for that reason.
What to review
In Spain, the Capital Companies Act does not allow shares to be issued that alter the proportion between nominal value and voting rights, which in practice rules out multiple votes, and admits non-voting shares only up to half of the paid-up capital, with a preferential minimum dividend. Here, control is separated from capital with non-voting shares, shareholder agreements or veto rights.
For a family business, the case illustrates how to separate control from capital: non-voting shares for relatives who do not manage, shareholder agreements or a family protocol. Each formula has costs: the non-voting shareholder depends on the will of whoever is in charge, which is why their economic rights are worth setting out in the articles of association. Anyone who holds shares in listed companies, directly or through funds, can check what voting rights they carry and who controls the company.
Paying for a share of a company is not the same as having a say in it.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.