On 12 October 2020 the Swedish Academy awarded the Economics Nobel to Stanford’s Paul Milgrom and Robert Wilson for improving auction theory. What they found and why it matters to business.
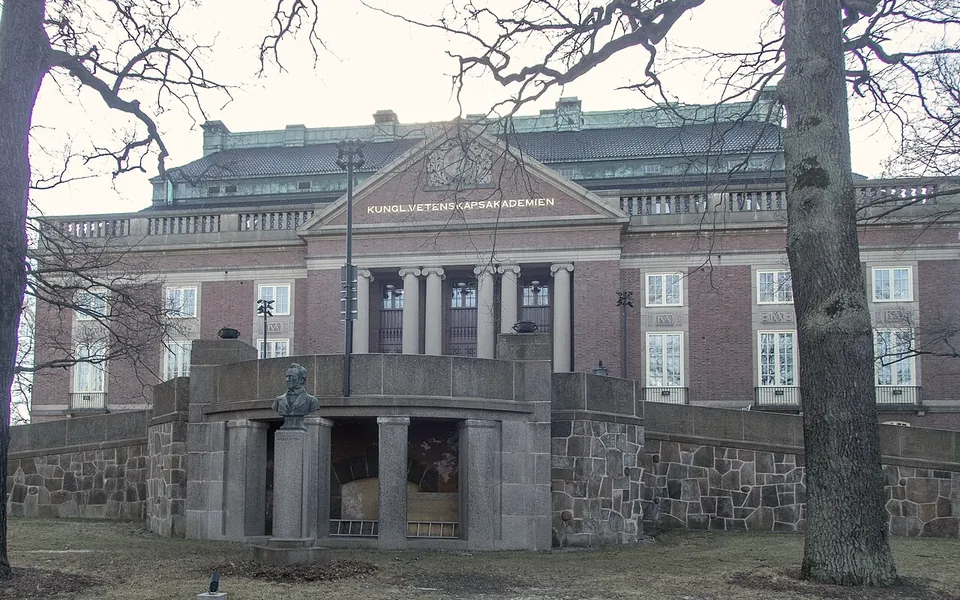
On 12 October 2020 the Royal Swedish Academy of Sciences awarded the Nobel Prize in Economics, officially the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel, to Paul Milgrom and Robert Wilson of Stanford University, “for improvements to auction theory and inventions of new auction formats”. The prize, 10 million Swedish kronor, a little over $1.1 million, is shared between them. Milgrom is a professor in the economics department and Wilson a professor emeritus at the Graduate School of Business.
What they found
An auction is a mechanism for setting a price when nobody knows exactly what the item is worth. Wilson studied objects with a common value, the same for everyone but uncertain, such as the mineral content of a mine being auctioned: each participant estimates it from their own data. He showed that rational bidders offer less than they calculate, because the winner is usually the one who made the most optimistic estimate and risks overpaying. This is known as the winner’s curse.
Milgrom extended the theory to more complex objects, whose value combines a common part and a private part that differs for each buyer. He analysed how the format affects the revenue a seller can expect when participants estimate what things are worth to others. The result is that the format matters: depending on how it is sold, the same object can earn the seller more or less.
Together they designed formats for selling many interrelated objects at the same time. The US authorities adopted one of them in 1994 to allocate radio frequencies to telecoms operators. In that format, the simultaneous multiple-round auction, all the lots are sold at once and over several rounds, so each participant sees what the others are bidding and adjusts their strategy, which is key when the value of one lot depends on the others. The European Union has also used their theories and methods to auction emission allowances.
Why it matters to business
The Academy says their discoveries have benefited sellers, buyers and taxpayers around the world. The same principles help explain processes that companies know well: licences awarded by the state, contracts put out to tender, and assets and businesses sold through competitive processes. In all of them a seller wants a good price and several buyers do not fully know the value of what they are bidding for.
For buyers, the lesson is Wilson’s: when value is uncertain, the winning bid tends to come from the most optimistic estimate, so it is worth setting a maximum price in advance and not being carried along by the competition. For sellers, it is Milgrom’s: the format, the timetable and the information given to participants influence the outcome, and a well-designed process attracts more competition than an improvised one.
What to review
If your company takes part in a tender or a sale process, or is preparing one, it is worth reviewing three things: what range of value is being used and on what data, how far you are prepared to go, and how the result will be compared with other alternatives, including not buying or not selling. It also helps to know who else is bidding and what information they have. Ask your adviser how it applies to your case.
A well-understood auction does not reward the highest bidder, but the one who best knows what the prize is worth.
This article is general information. It is not legal, tax or investment advice, and it does not take anyone’s particular circumstances into account.